Part-time power has no commercial value, which is why wind and solar are utterly pointless. Every single MW of wind or solar has to be “backed up” with another MW from a dispatchable source, which in the main means coal, gas, nuclear or hydro.
Contemplate where your power comes from on a calm night, and chances are you’ll realise that the grand wind and solar ‘transition’ is pure hoax.
At this point in the narrative the cultist starts ranting about giant batteries, green hydrogen and (now and again) pumped hydro, ignorant of the fact that batteries don’t generate electricity, that green hydrogen is a myth and that pumped hydro uses more electricity than it ever returns.
In the piece below, Francis Menton picks up the thread with a full-frontal assault on the nonsense that net-zero carbon oxide gas emissions targets can be satisfied using wind and solar alone.
Why There Will Never Be A Zero Emissions Electricity System Powered Mainly By Wind And Sun
Manhattan Contrarian
Francis Menton
21 September 2024
“Net Zero” — That’s the two-word slogan that has been adopted as the official goal of every virtuous state or country for decarbonizing its energy system. The “net” part is backhanded recognition that some parts of the energy system (like maybe air travel or steelmaking) may never be fully de-carbonized. Thus some kind of offsets or indulgences may need to be accepted to claim achievement of the goal.
But the “net” thing is not for the easy parts of decarbonization. And by the easy parts, I mean the generation of electricity, and the powering of anything that can be run on electricity or batteries. In electrifiable parts of the energy system, there is to be no tolerance for “net”; only “zero emissions” will do. The official line is that zero emissions electricity is easy and cheap because it can be provided by the wind and sun.
The official line is wrong. As the build-out of these wind and solar generation systems continues to progress, it has become increasingly obvious that there will never be a zero-emissions electricity system powered mainly by wind and sun.
The reason should be obvious to everyone although, for some reason I cannot understand, it is not. The reason is that the intermittency of wind and solar generators means that they require full back-up from some other source. But the back-up source will by hypothesis be woefully underused and idle most of the time so long as most of the electricity comes from wind and sun. No back-up source can possibly be economical under these conditions, and therefore nobody will develop and deploy such a source.
This issue has already arisen in many places, as increasing generation from wind and sun has put natural gas power plants into back-up mode, running half or less of the time.
Now consider how things are supposed to proceed as we move to zero-emissions electricity. First, we build more and more wind and solar facilities. Second, we disallow natural gas or any other hydrocarbon fuel as the back-up. Now the back-up must itself be zero-emissions, and also dispatchable.
In New York, our regulators have devised the acronym DEFR (“Dispatchable Emissions-Free Resource”). Several possibilities have been suggested as the DEFR, the main ones being nuclear, hydrogen, and batteries. All possibilities for the DEFR that have been suggested share the characteristic that they don’t exist today at anything close to the scale that will be needed to fully back up an electricity system powered mainly by wind and sun. In other words, somebody will have to make a huge investment in one or more of these things on a grand scale if we are to have an electricity system powered mainly by wind and sun.
Given New York’s political environment, the regulators who have raised the need for the DEFR have generally buried their discussion of the subject deep in lengthy documents. Roger Caiazza, the Pragmatic Environmentalist of New York, has done yeoman’s work in digging up and highlighting these items. Roger has created a “Dispatchable Emissions Free Resource Page” where he has accumulated the key information.
For example, we have the Scoping Plan of the Climate Action Council, which Roger describes as “the ‘official’ Hochul Administration strategy description of the Climate Act transition.” The document is some 800+ pages of text plus appendices. Somehow, Roger made it to page 49 of Appendix G, where he found this quote:
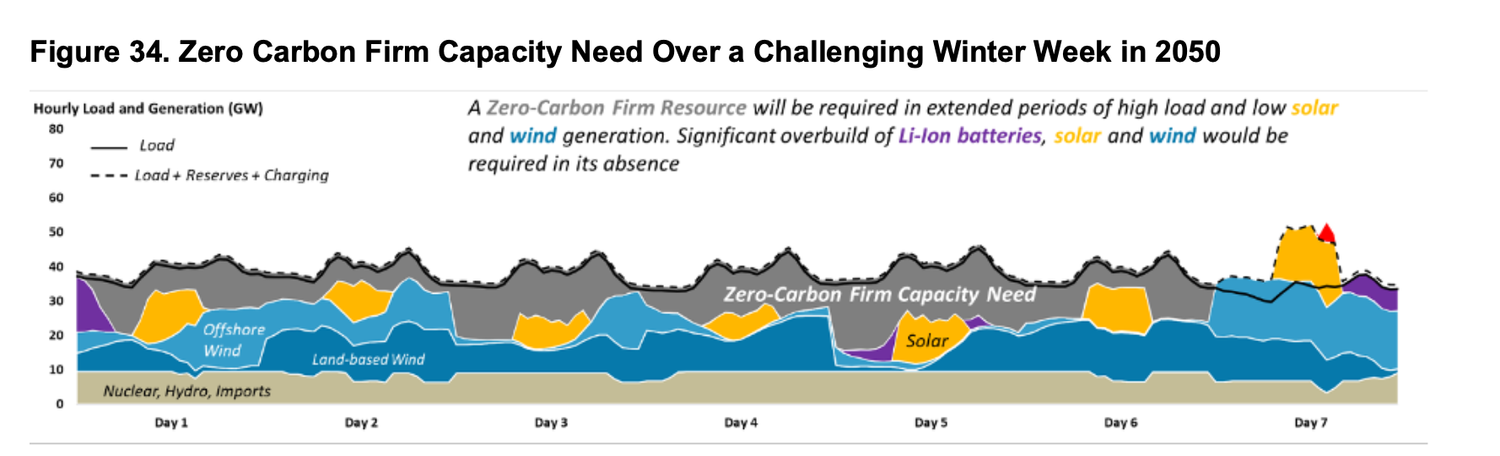
During a week with persistently low solar and wind generation, additional firm zero-carbon resources, beyond the contributions of existing nuclear, imports, and hydro, are needed to avoid a significant shortfall; Figure 34 demonstrates the system needs during this type of week. During the first day of this week, most of the short-duration battery storage is quickly depleted, and there are still several days in which wind and solar are not sufficient to meet demand. A zero-carbon firm resource becomes essential to maintaining system reliability during such instances. In the modeled pathways, the need for a firm zero-carbon resource is met with hydrogen-based resources; ultimately, this system need could be met by a number of different emerging technologies.
Here is the Figure 34 that they mention:
It may be a little hard to read, but the dark gray is what they label the “Zero-Carbon Firm Capacity Need.” The width of that dark gray section gets up to well over 20 GW during the illustrated low wind/sun week. For reference, New York State’s current average electricity usage is well less than 20 GW. Meanwhile, even during this low wind/sun week there are times when this DEFR is not called on at all, and other times when it is called on for only a few GW.
So without saying so in as many words, they are telling us that as part of a predominantly wind/sun system we will need to build DEFRs of capacity equal to or greater than our entire current average electricity usage. But if the electricity system is powered mainly by wind and sun, then by definition the DEFRs are only going to operate a minority of the time.
We will have now built an entire fleet of new nuclear power plants capable of fulfilling our entire peak electricity demand. Or maybe it’s an entire fleet of new hydrogen power plants of same capacity, or an entire fleet of grid-scale batteries of same capacity, only to keep them idle most of the time.
These are extremely capital-intensive facilities, which can only hope to be economical if they are operated to as much of their capacity as possible. Instead the proposal is that will be intentionally kept idle most of the time.
Who is going to make the investment in these DEFRs that will be kept mostly idle. Certainly, no private investors will do it without enormous government subsidies.
And if we were to build an entire system of these DEFRs capable of supplying all of our electricity needs to back up worst-case wind/sun lulls, wouldn’t it make far more sense just to leave out the wind and solar generation and go with the DEFRs all the time? Of course it would.
At some point this is going to become too obvious to ignore. Manhattan Contrarian
“Whether it is the unprecedented subsidies for renewable energy or the unprecedented war on American energy, the Biden administration’s policies are behind the increase in America’s electricity prices.”
During the first three years under Biden vs. last three under Trump, average wholesale electric prices in the seven U.S. independent or regional service areas have increased by 72%. Retail prices are also higher. The average 2024 U.S. residential rate to date is 24% higher than in 2020. For all end users—residential, commercial, industrial, and transportation sectors—prices are up 23%.
This rate surge reflects the massive renewable energy subsidies authorized in the Inflation Reduction Act of 2022, signed by President Biden, that tripled the outlay of such federal largesse. Another factor is the administration’s natural gas policies, which banned imports of Russian oil, liquefied natural gas, and coal; joined with the European Commission to reduce Europe’s dependance on Russian oil; and put a pause on LNG permits. Natural gas combined cycle, the the technology of choice in a free market, is as cheap as ever, representing the path not taken.
Whether it is the unprecedented subsidies for renewable energy or the unprecedented war on American energy, the Biden administration’s policies are behind the increase in America’s electricity prices.
Wholesale Prices Up 72% Wholesale electricity prices are the best indicator of the direction of electricity prices. State regulations on retail prices often shield consumers from immediate exposure to rising energy prices. Eventually, though, consumers will bear the full brunt of higher wholesale electricity costs either through higher retail electric prices, lower income, or higher prices for other goods and services.
Figure 1 shows the “all-in” energy prices for the seven U.S. Independent System Operators or Regional Transmission Organizations. These areas cover about 70% of the electricity used in the United States, which roughly corresponds to the percent of U.S. population in the service areas.
The average wholesale price of electricity across these service areas from 2021 to 2023 was $70 per megawatt hour, up from $41 from 2018 to 2020. This means the average wholesale electricity price during the first three years of the Biden administration jumped 72% over the average price of the last three years of the Trump administration.
ERCOT, which covers most of Texas, had the highest average wholesale price over the last three years at $117. It also had the highest three-year increase at 208%. ISO New England had the second highest average price at $81, followed by California ISO at $80. CAISO also had the second highest three-year price increase at 81%. New York ISO was next averaging $68, although prices in New York City were considerably higher at $80. The service areas for these and other service entities are shown below (Figure 2).
Retail Prices Up 20%
Despite the regulatory brakes on increases, Figure 3 (below) shows that retail prices have also been rising rapidly during the Biden administration.
For 2024 year-to-date, residential electricity prices have averaged 16.34 cents per kilowatt hour. This an increase of 3.19 cents, or 23%, from 2020, the last year of the Trump administration. For all end users in the residential, commercial, industrial, and transportation sectors—prices are up 2.39 cents, or 23%, during the same period. Retail prices rose much more slowly during the Trump administration. Residential prices rose only 5% and for all end users only 3%.
There is no doubt that these increases in end-user electricity prices are only the beginning. The recent increases in wholesale electricity prices are already baked into the future retail electricity prices. Regulators will consider the higher costs that generators are incurring and increase future retail prices.
Biden’s Energy Policies At Fault
Across the news, headlines scream about the housing affordability crisis. “Housing on the ballot: Harris, Trump push different plans for tackling housing affordability crisis,” says AP News. The Economic Times asks the question, “US housing crisis: Why is America facing shortage of homes and will this crunch revive inflation?”
Yet very few are talking about a crisis of energy affordability. This is interesting, considering housing prices are not increasing much faster than electricity prices. For instance, housing prices in Texas’s four largest metro areas (Dallas/Fort Worth, Houston, Austin, and San Antonio) are up 25% over the last four years, not much more than U.S. residential electricity prices and far less than wholesale prices. Perhaps the reason for this difference is that most people who know what is causing electricity prices to increase do not want to talk about it.
The Cost of Renewable Energy Subsidies
In a recent article, The Problem with Solar, the authors wrote that the problem with solar is “it’s basically free—but at the same time it’s hideously expensive.” They got it half right.
Their reason for optimism about solar is “the cost curves for photovoltaic generation have come down farther and faster than anyone thought possible. Cue the breathless headlines: “the age of basically-free solar power for all is upon us!” This is a very common message in both media and academia these days. The only problem with it is that it is completely wrong.
Solar, like wind, can appear cheap when one focuses only on the generation of electricity taking place in the moment. The sun shines, the wind blows, and electricity is generated. No fuel costs at all. Yet this misses the 90% of the renewable iceberg that is underwater.
The only reason solar and wind are part of the U.S. commercial electric grid is because of subsidies. Figure 4 above shows that renewable energy subsidies last decade were double those for fossil fuels and five times those for nuclear. But this does not show the full story. Bennett et al. give us the rest in Figure 5 (below).
From 2010 through 2019, solar received $82 per megawatt hour of electricity generated. That is 42 times the amount of subsidies per megawatt hour nuclear received, 112 times coal, and 211 times oil and gas. For wind, its multiples were 10 times nuclear, 26 times coal, and 48 times oil and gas. The “free” wind and solar generation actually cost taxpayers $74 billion last decade in federal subsidies, without including the cost of the electricity or state and local subsidies.
As costly to taxpayers as renewable energy subsidies were last decade, this decade the costs are exploding. Figure 4 shows that renewable subsidies will more than triple this decade and will be ten times more than both fossil fuels and nuclear, not taking into account the per megawatt hour measure of the subsidies. The primary reason for the increase in renewable energy subsidies this decade is the Inflation Reduction Act.
Figure 6 below shows that from 2017 through 2022, the year President Biden signed the Inflation Reduction Act into law, the average annual cost of renewable energy subsidies was $8.1 billion. However, once the IRA went into effect in 2023, the average cost of renewable energy subsidies tripled to $24.9 billion annually. The harm that renewable energy was doing prior to the IRA has accelerated with the cost of maintaining grid reliability rapidly increasing because of the growth of renewables.
The Reliability Cost of Renewable Energy
A remarkable event occurred in 2023; coal, nuclear, and renewable energy converged to become essentially equal generation sources on the U.S. grid. This would have been unthinkable a quarter of a century ago. Figure 7 shows the growth of renewables from essentially zero generation to almost equaling coal, which is generating less than half of its output from 2001, and being only slightly below nuclear.
This convergence signals a new chapter in the long-running battle to maintain grid reliability in light of two major generation sources–wind and solar–that cannot be counted on to generate electricity when it is needed.
The key feature of wind and solar as generation sources is their intermittency. This means that unlike coal, natural gas, and nuclear generation, they are only available when nature cooperates. This adds tremendous—and generally unacknowledged—costs to maintaining the reliability of the grid.
Going back to the article, The Problem with Solar, its authors explain why a seemingly inexpensive energy source is nothing of the kind:
The answer is that, yes, solar power generation has become close to free… but only when the sun is shining. Which happens some of the time, but not all of the time, not predictably and not necessarily at the times people need power the most.
The dirty little secret is that, at the scale relevant to most people, solar generation’s cost advantage is sort of beside the point. For solar to serve as the backbone of a grid, it needs to be backed with storage. That can come in the form of batteries, hydrogen, or pumped hydro. All of these are expensive; none of them scale. Storing a kilowatt-hour of electricity in a chemical battery costs an order of magnitude more than just generating it in a nuclear power plant. Which is why a 100% solar grid would be insanely expensive, even though generating solar power is basically free.
This also applies to wind, and explains in laymen’s terms what scientists have said for years; it is a well-known fact that the reliability value of renewable energy declines as its grid penetration increases. Which means that either batteries or natural gas backup generation must be on standby for those periods when the wind doesn’t blow or the sun doesn’t shine. While batteries are insanely expensive, backup natural gas generation is merely stark raving mad expensive.
Energy researcher Robert Bryce explains why continuing the growth of renewables is not only expensive, but also impossible. Bryce examined a 2023 report by Tesla that claimed that we could transform the world’s electric grid in about 20 years to support a “sustainable energy economy,” one that relies almost completely on renewables. Bryce highlights Tesla’s claim “that building the infrastructure for a ‘sustainable energy economy will cost $10 trillion.’” At $500 billion a year, that is 20 times the current level of renewable energy subsidies. Bryce also shows that electricity from solar is getting more, not less, expensive. He then explains the physical impossibility of Tesla’s plan:
Nevertheless, it only takes a minute to understand why that 240 TWh of storage is so gobsmackingly silly. First some basics. Recall that 1 TWh is equal to 1,000 gigawatt-hours (GWh) and that one Gigafactory can manufacture about 50 GWh of batteries per year. Tesla currently has 5 Gigafactories. Thus, Tesla’s current battery storage output is, in rough terms, 250 GWh per year. Now recall that the Master Plan requires 240 TWh, which is 240,000 GWh. Therefore, as can be seen in the graphic directly above, producing 240,000 GWh of battery capacity would require the output of all of Tesla’s existing Gigafactories for the next 960 years.
The high costs, failing reliability, and physical challenges of building and maintaining a grid dominated with wind and solar generation is not just a problem for the future, however. The growth of renewables fueled by government subsidies—and exacerbated by Biden’s Inflation Reduction Act—is causing major problems today. Texas provides a real-life example.
The Texas Example
As noted above, Texas leads the nation with a 208% increase in wholesale electricity prices over the last three years. Why would Texas, which leads the nation in natural gas production and has long relied on it to generate electricity, experience price hikes because of wind and solar generation?
The short answer is that Texas also leads the nation in generating electricity from renewable energy. In 2023, 34% of electricity generated in Texas came from wind and solar. The longer answer also helps explain why Texas is experiencing more reliability problems because of renewables than any other state.
The ERCOT portion of the Texas grid, which serves 27 million customers, is the only ‘energy-only’ electric market in the United States. What this means is that decisions about building new generation are left to the market, not to regulators as is done in other states. This worked well in Texas for about 15 years, as long as market prices were allowed to balance the needs of generators and consumers. Investors found many opportunities to profitably invest in new, primarily natural gas, generation that led to robust grid reliability and affordable prices.
However, as renewable subsidies and renewable generation continued to grow, they distorted market prices and led to almost all new investment going to renewables. Over the five-year period from 2018 to 2023, generation from coal-fired plants fell 34%, nuclear generation was down 1%, and natural gas generation was up only 17%. Meanwhile, generation from wind increased 55% and solar generation was up 900%.
The situation is getting worse. ERCOT forecasts renewable generation will increase by 58,654 megawatts through 2029 (wind by 3,628 megawatts, solar by 36,868 megawatts, and batteries, which also receive billions in subsidies, by 18,158 megawatts). Thermal resources, however, will only increase by 1,074 megawatts. Renewables are projected to make up 98.2% of new generation on the Texas grid over the next five years.
The reason for this shift to renewables is simple. It is now more profitable in Texas to build new solar and wind generation than natural gas. This is not, though, because renewables are inherently profitable investments. It is solely because of renewable subsidies. In 2024, the subsidies will increase the return on investment for generators by about 30% above what they earn selling electricity.
The result of the shift to wind and solar has been a rapid decline in grid reliability. There are two types of reliability problems caused by renewables. The first is caused directly by the intermittency of renewable generation. When changes in weather conditions cause declines or outages of renewable generation, complicated and costly steps must be taken to bring backup natural gas generation online.
The second problem is the long-term decline in reliability caused by renewable energy subsidies. This was on display in 2021 when, thanks largely to renewables, Texas experienced perhaps the worst blackout in American history during Winter Storm Uri. When wind and solar generation failed during the storm, there was not enough backup generation to compensate. Though natural gas generation also experienced problems, if the money that had been invested in renewables had instead gone to natural gas—or nuclear or coal, there would have been enough generation to possibly avoid the blackout entirely, or at least to ensure that Texans only experienced temporary 30-minute rolling blackouts.
Dealing with both types of reliability problems is “insanely” expensive. And because of Texas’s market design—and the way Texas politicians have chosen to deal with the problem, the costs are more transparent than they are in other states.
The best way for Texas to deal with its growing reliability problem would have been to eliminate all state and local renewable subsidies and force renewable generators to pay for the cost imposed on the grid by federal renewable subsidies. Instead, Texas politicians decided to double down on subsidies by giving them also to thermal generators. Texas began this process about 2014 when the reliability issues of wind generation and renewable subsidies began showing up on the ERCOT grid.
Then in 2019 politicians and regulators greatly increased the thermal subsidies, and did so again in 2021 and 2023 because of the Uri grid failure (Figure 8). The cost of Texas thermal subsidies in 2023 was $16 billion, in addition to the $4 billion renewable received. This effort, mistaken as the approach might be, demonstrates the high costs renewables are imposing on the U.S. electric grid, why Texas led the nation in wholesale price increases over the last three years, and why electricity prices have risen during the Biden administration.
A Brief Word about Natural Gas Prices
According to Potomac Economics, “There are two primary drivers of [electric] market prices: natural gas prices and the number of hours of supply shortages during the year.” There has been a correlation between gas and electricity prices over the period this paper examines, but it has lessened as the growth of renewables created new cost-increasing grid shortages that did not previously exist.
One of these new shortages is the “duck curve,” the time when there “is an increased need for electricity generators to quickly ramp up energy production when the sun sets and the contribution from PV falls.” This sunset shortage did not exist before solar came online. As the U.S. Department of Energy explains, “High solar adoption creates a challenge for utilities to balance supply and demand on the grid.”
Wind has created similar shortages. Wind output can be reduced over long periods of time, as it was in 2023. But it can also happen daily. Whether these shortages are long- or short-term, expected or unexpected, it costs a lot of money to have alternate generation on standby and even more when it is necessary for the generation to run. These renewable-induced shortages have added to the cost of electricity as renewable generation grid penetration has increased while reducing the correlation between natural gas and electricity prices.
Whatever the correlation is between natural gas and electricity prices, the Biden administration’s energy policies have had a significant effect on natural gas prices. Rep. Dan Newhouse summed up the administration’s Unprecedented War on American Energy: “From cancelling the Keystone XL Pipeline to revoking leases for oil, gas, and mining across the West, it is clear the president’s unprecedented war on domestic energy producers has put the United States in a vulnerable position.” All of this and other policy decisions raised natural gas prices. Thus, to the extent that natural gas prices correlate to increases in electricity prices, this still points to the Biden administration.
Conclusion
Whether it is the unprecedented subsidies for renewable energy or the unprecedented war on American energy, the Biden’s administration’s policies have led to a significant increase in America’s electricity prices.
————————-
Bill Peacock is the policy director of the Energy Alliance, a project of the Texas Business Coalition to raise awareness of issues about the energy market that matter the most to consumers: Reliability, Affordability, and Efficiency
Whenever discussing renewables subsidies on the internet, there is a form of Godwin’s Law that means it is inevitable that someone will come along and say: “Ackshually, fossil fuels are subsidised more than renewables,” or words to that effect, as shown in this example. I have often thought the claim to be bogus, but until now had never dug into the detail to prove the case one way or the other.
Energy is one of the elementary foundations of modern society. Almost any activity you can think of requires energy input of some type or other. Factories need energy to make things. Offices need energy for heating, lighting, cooling and running computers, as do our homes. Hospitals need energy to run operating theatres. We need energy to go to work or visit friends and family, whether we travel by car or train. We need energy to do the family shopping, cook, to travel to the gym, cinema, or restaurant. Energy is fundamental to every economic and social interaction, so it would not be surprising if energy were subsidised. Expensive energy is like a tax on our very existence, so taxes on energy act as a drag on society.
It is therefore vital that we get to the bottom of the claimed fossil fuel subsidies in the U.K.
What is a Subsidy?
In simple terms, a subsidy is when the Government pays (or mandates consumers to pay) for an activity to occur that otherwise would not happen if the market were left to its own devices. Examples might include grants to theatre companies or awarding CfD contracts to offshore wind.
A tax is where the Government levies an extra charge on a transaction or activity. For instance there is Value Added Tax, levied at 20% for sales of most goods and services. There are also special taxes such as levies on alcohol and tobacco and of course income tax. Reduced rates of tax are still taxes, quite the opposite of subsidies. No taxes and no subsidies represent a neutral position.
When it comes to oil and gas, the definition of a subsidy becomes a little controversial. The International Energy Agency (IEA) defines fossil fuel subsidies as “measures that reduce the effective price of fossil fuels below world market prices”. It is certainly true that some countries, such as Russia and Iran, do subsidise hydrocarbons according to the IEA’s definition. Interestingly, the Government said in 2021 the “U.K. does not give any subsidies to fossil fuels” and the U.K. does not appear on the IEA’s Top-25 list from 2022 of countries that subsidise fossil fuels (see Figure 1).
Figure 1 – IEA Top-25 Countries Subsidising Fossil Fuels
However, it should be noted that in the database buried in the IEA’s website it does claim that the U.K. offered fossil fuel subsidies of around £6 billion in 2022, but none in any other year. There must be something about its definition that omits the U.K. from its Top-25 graphic.
Where do the Claims of U.K. Fossil Fuel Subsidies Come From?
Given the Government statement and the U.K. not appearing in the IEA’s list of top subsidisers, we need to look at where these claims of massive subsidies come from. Unfortunately, the idea that the U.K. heavily subsidises fossil fuels has a long history. This 2013 article from the Guardian claims the U.K. is “subsidising its coal, oil and gas industries by $4.2 billion (£2.6 billion) a year”. The Guardian has produced similar articles over the years such as this one from 2019 claiming “the U.K. leads the European Union in giving subsidies to fossil fuels” and this one from 2023 claiming “the U.K. Government has given £20 billion more in support to fossil fuel producers than those of renewables since 2015”. Note that they use the words “support” and “subsidy” almost interchangeably, eliding so called “tax-breaks” with subsidies. The Guardian is not the only publication making this type of claim. Politicoalso got in on the act in 2021 claiming that Britain “supports the fossil fuel industry through tax breaks and subsidies… to the tune of £10bn a year”.
When digging into the articles, you can see that their definition of subsidy includes consumers or producers paying less tax on fossil fuels than the authors believe appropriate. At the risk of repeating myself, paying less tax still means the activity is taxed, which is the direct opposite of a subsidy. Paying less tax than an arbitrary level is not a subsidy. Even paying zero tax is a neutral position and certainly not a subsidy.
How Big are Fossil Fuel “Subsidies”?
The Politico article linked above refers to data from the OECD to support its £10 billion (for 2020) claim. By digging into a more up to date version the data, we can evaluate the veracity of the claims. Broadly speaking the “subsidies” or support mechanisms are broken into two categories: producer subsidies and consumer subsidies.
Using the data for 2022, the total alleged support for oil and gas producers amounts to £3.1 billion. The largest component of this total is £2.25 billion of tax relief for decommissioning. This arrangement allows companies to claim capital expenditure connected to decommissioning old fields against corporation tax. For oil and gas companies, decommissioning their fields is a normal business expense. In normal company taxation, business expenses are deducted before calculating taxable profits. There is nothing to suggest that deducting decommissioning expenses before calculating taxable profits is anything other than normal business practice and is certainly not a subsidy. A further £0.85 billion of “support” is alleged because companies can treat investment in new fields as a business expense to set against the Supplementary Charge that oil and gas companies are subject to on their profits. Again, this is not very different to the investment allowances made to companies in other industries and does not amount to a subsidy.
Using 2022 data again, there is about £12.9 billion of claimed routine consumer support for fossil fuels. £7.8 billion of the total comes from consumers being charged 5% VAT on their domestic energy bills and not the normal 20% rate. It should go without saying that 5% VAT is still a tax, quite the opposite of a subsidy. A further £3.5 billion of the alleged support comes from fuel duty relief where some types of fuel pay less fuel duty for some uses than others. Again, some fuel duty applies, just not the full rate. This is not a subsidy; it is just paying less tax. Another £1.4 billion of “support” comes from reductions in the Climate Change Levy. Ironically, much of this support is granted to organisations with Climate Change Agreements to reduce energy use or CO2 emissions. In the crazy world of climate activists, paying a lower Climate Change Levy by agreeing to reduce emissions amounts to a fossil fuel subsidy. Finally, a further £0.2 billion of consumer support comes through the Warm Home Discount. This is a reduction in energy bills for older pensioners and other vulnerable people and it is probably justified to term this a subsidy, although it applies to gas and electricity from all sources including renewables, not just fossil fuels. Out of a total £16 billion of supposed subsidies, only £0.2 billion could be reasonably termed a subsidy and an indirect one at that.
However, there is a ‘but’ and it is quite a big but because we also need to consider one-off consumer support schemes. There was £19.4 billion on the Energy Price Guarantee for domestic consumers, £2.6 billion on the Energy Bill Relief Scheme for non-domestic consumers and a further £2.6 billion on the Energy Bill Support Scheme. These schemes amount to a total of £24.6 billion and there is a case to classify this money as some sort of subsidy. However, these schemes should probably be referred to as indirect subsidies because they covered all forms of generation, not just fossil fuels. Note that as Figure 1 shows, this support did not meet the IEA definition of a subsidy, or the U.K. would have appeared in about 12th place. We should also bear in mind these schemes were one-off responses to a crisis and are no longer in operation.
Taxes on Fossil Fuels
If we are to get a complete picture we should also consider the taxes the U.K. levies on fossil fuels. These can be split into two categories: producer taxes and consumer taxes.
Oil and gas producer taxes comprise ring fence corporation tax, the supplementary charge (extra corporation tax), petroleum revenue tax and the energy profits levy (also known as the windfall tax). According to the OBR, the total receipts for these taxes rose sharply from £2.6 billion in 2021-22 to £9.8 billion in 2022-23 (the most comparable year to calendar 2022). Those who claim we subsidise fossil fuels are effectively saying we should increase these taxes by the £3.1 billion “support” identified by the OECD above. Once again, paying less tax than some arbitrarily defined level is not a subsidy.
The ONS publishes the cost of environmental taxes, many of which can be characterised as consumer taxes on fossil fuels. These include direct taxes on fossil fuels that raised the following amounts in 2022:
Fuel duty, £24.8 billion. Those who say we subsidise fossil fuels would add the £3.5 billion of fuel duty relief identified by the OECD to this already massive tax, making it much more expensive to move around.
Emissions Trading Scheme which raised £4.6 billion including U.K. and EU schemes.
Climate Change Levy (CCL), £2.1 billion. Those claiming massive fossil fuel subsidies would add the £1.4 billion CCL reductions identified above to this already significant tax, effectively cutting incentives to reduce emissions.
In addition, there are indirect taxes on fossil fuels that raised even more money in 2022:
Road Fund Licence, £5.2 billion (remember this tax does not apply to electric vehicles yet).
Air Passenger Duty, £3 billion.
The Plastic Packaging Tax brought in £0.3 billion. Plastic is made from fossil fuels, so this is effectively another tax on fossil fuels.
This gives a total of £31.5 billion of direct taxes and a further £8.5 billion of indirect consumer taxes on fossil fuels.
Finally, VAT is levied on domestic energy, petrol and diesel which is another direct tax that falls on fossil fuels. However, I cannot find a reliable data source that gives an analysis of VAT receipts arising from hydrocarbons so we should simply note VAT raises about £160 billion in total each year and fossil fuels will contribute a significant portion of that total.
Conclusions
This analysis is summarised in Figure 2 below.
Figure 2 – UK Fossil Fuel Subsidies and Taxes 2022 (£bn)
First, we can dismiss the so-called subsidies for producers as normal business expenses deducted from taxable profits. We can also dismiss all but the £0.2 billion Warm Home Discount ongoing consumer “subsidies” as simply lower taxes for some uses of fuel. Tax is still tax and lower tax is not a subsidy. If we are generous to those who claim we subsidise fossil fuels, we could note that in 2022 there was about £24.6 billion of one-off indirect subsidies. However, these schemes are now no longer in operation.
On the tax side of the ledger, we have £9.8 billion in producer taxes, £31.5 billion of direct consumer taxes and a further £8.5 billion in indirect consumer taxes, plus an unknown amount of VAT. Even in an exceptional year when the various energy bill support schemes were in place, taxes exceeded the alleged subsidies by a wide margin.
Now the energy crisis has subsided we are left with just £200 million of indirect subsidy to help the elderly and most vulnerable with their energy bills offset by close to £50 billion of direct and indirect taxes as shown in Figure 3.
Figure 3 – Expected UK Fossil Fuel Subsidies and Taxes 2024 (£bn)
However, we should note it is likely the fossil fuel tax take will fall with lower oil and gas prices. Production will likely decline due to a lack of investment driven by the 78% marginal tax rate on profits, leading to a bigger fall in producer taxes. On the other hand, it is rumoured that the Chancellor will increase Fuel Duty in the Budget. High taxes mean high prices which in turn function as a tax on the rest of the economy leading to steady, inexorable decline. If we want a thriving economy, we should be cutting taxes on energy, not increasing them. Note again, lowering taxes is not a subsidy. Zero tax is not a subsidy, it is a neutral position. Remember this when some activist claims we subsidise fossil fuels.
I was privileged to have the opportunity to study science at university, and I have always been particularly interested in taxonomy that is naming, defining and classifying groups of organisms based on shared characteristics. This is fundamental to knowing the distribution and abundance of animal species, and how this might change, for example, following severe coral bleaching.
Early in my career I was a field biologist in Madagascar. After three years I was moved to Nairobi, the capital of Kenya, and from there I travelled all over Africa collecting plants and pressing them, but mostly species of insect, which after killing, pining and drying if it was an adult, or pickling if it was an immature, I would post the specimens to experts at the British Museum in London or the Smithsonian Institute in Washington DC. That was back in the 1980s, for seven fantastic years.
Good work boots are important for this type of outdoor work, as was a foldable magnifying glass. So often, being able to count, for example, the number of spatulas on the third instar larvae, was important to know whether a specimen was worth collecting, or not. It is much the same in marine biology. I am learning that, for example, accurately counting the number of tentacles on a polyp is the easiest way to distinguish a hard coral from a soft coral.
Of course, fundamental to current climate science politics is knowing the percentage hard coral cover at the Great Barrier Reef. It is quoted everywhere from UNESCO reports to Peter Ridd’s YouTube videos. I worry though that those doing the counting in the field may not be provided with the most basic instruments for getting this right, and then there is the importance of having a specimen lodged somewhere of each species, or at least a photograph. If the overall percentage, and how it is trending, is to be at all accurate it must begin with a reliable identification.
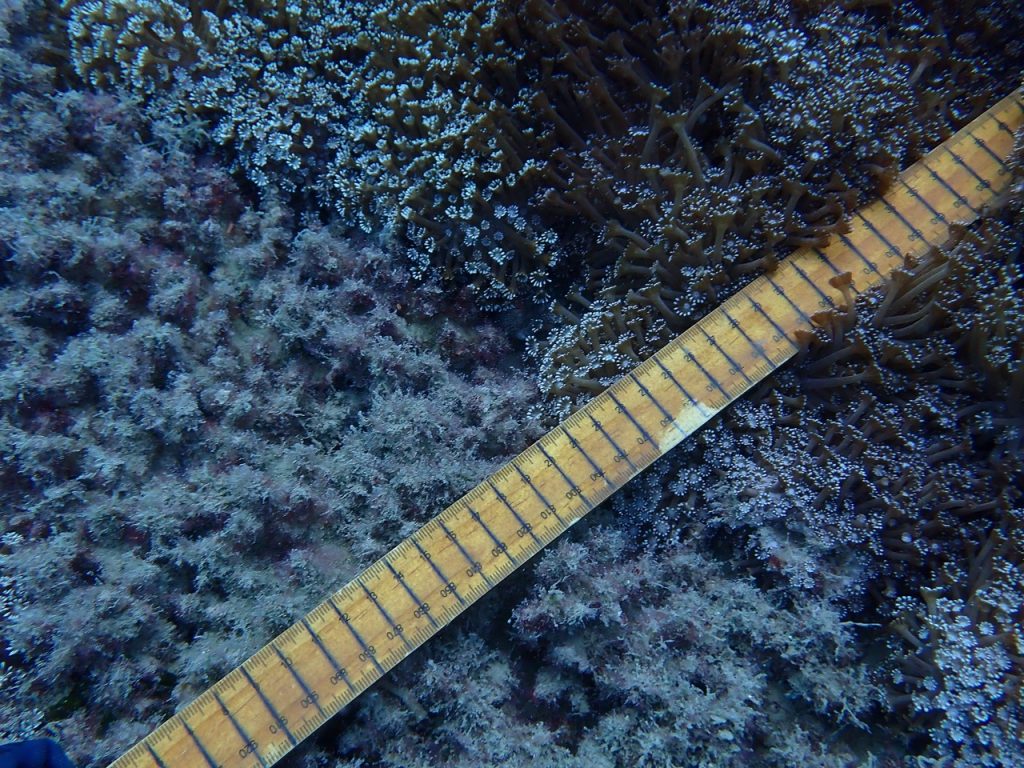
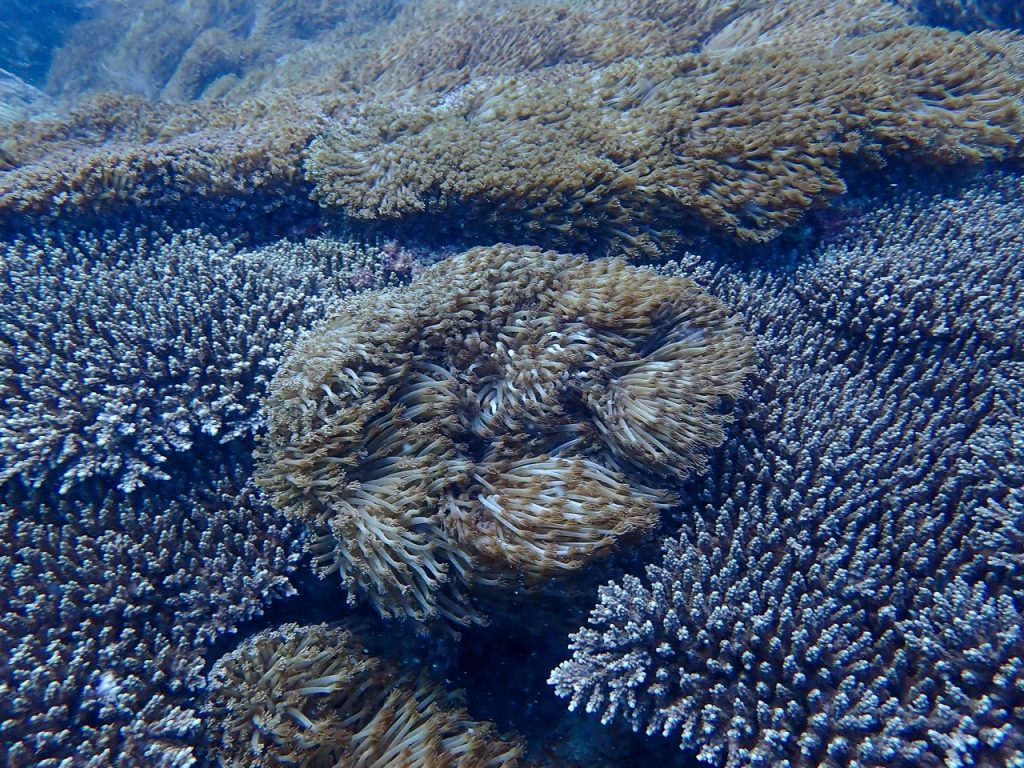
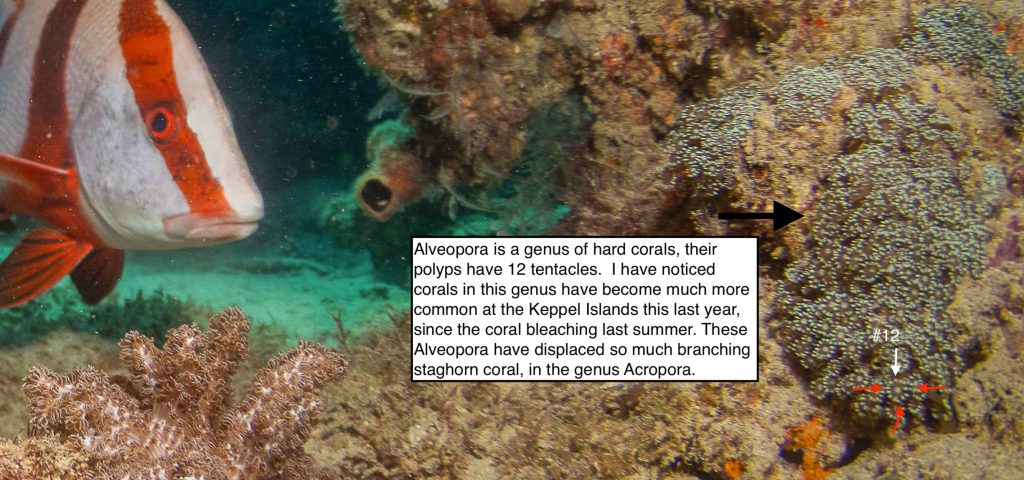
In the textbook about classifying soft corals by Katharina Fabricius and Philip Alderslade, they explain that hard corals in the genus Goniopora and Alveopora are often mistaken for soft corals, when the hard exoskeleton of calcium carbonate is invisible under a thick layer of expanded polyps. In fact, it is critical to count the tentacles on the polyps: soft corals have 8 tentacles, Gonipora have 24 tentacles and Alveopora 12. Given the polyps of many of these species are only a few millimetres in diameter it is impossible to know how many tentacles exist without a form of magnification.
I use my Olympus TG6 underwater camera, as I once used a magnifying glass. It can provide magnification up to 44 times, which is rather a lot.
What happened underwater at the Keppel Island reefs this last year is that first, all the corals bleached a stark white. That was reported in the New York Times in March, I was first able to photograph this in April. Then many of the dominant branching hard corals – the Acropora – they began to die.
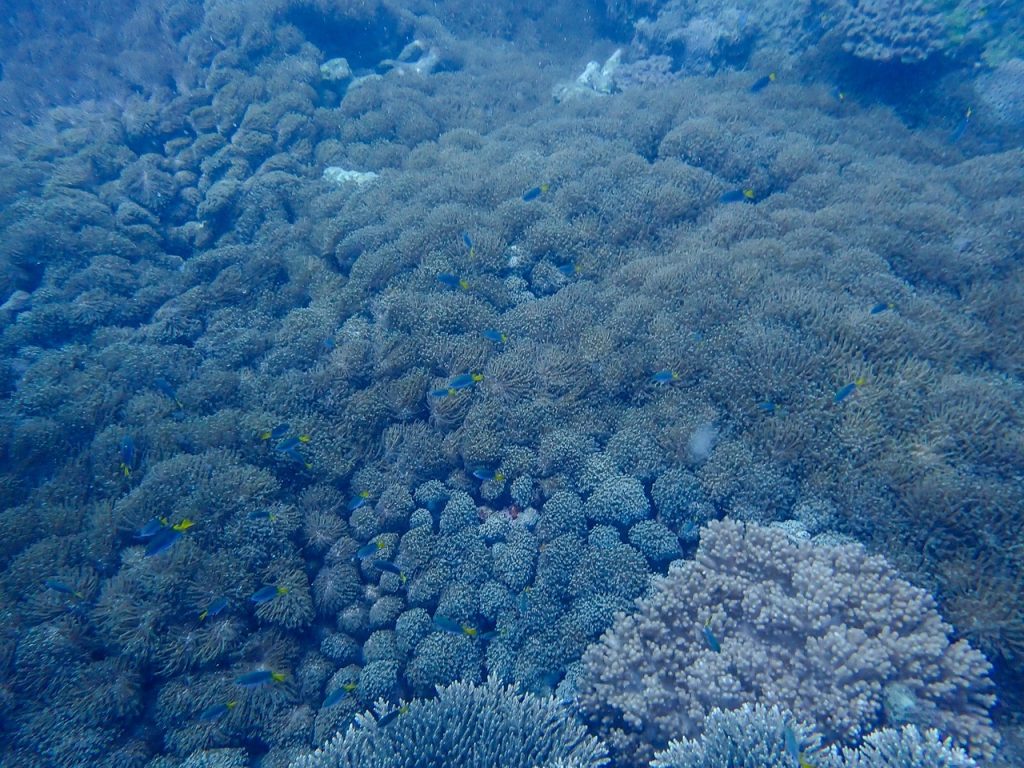
These branching Acropora became infested with what are called macroalgae. It was like these corals became covered in a light green moss. That attracted what are called the grazing herbivores – algae eating fish including oh so colourful surgeon fishes. Of course, with all the little fishes getting fat grazing the macroalgae, soon there were schools of fish-eating fish including yellow-tailed barracuda; that grew bigger and bigger.
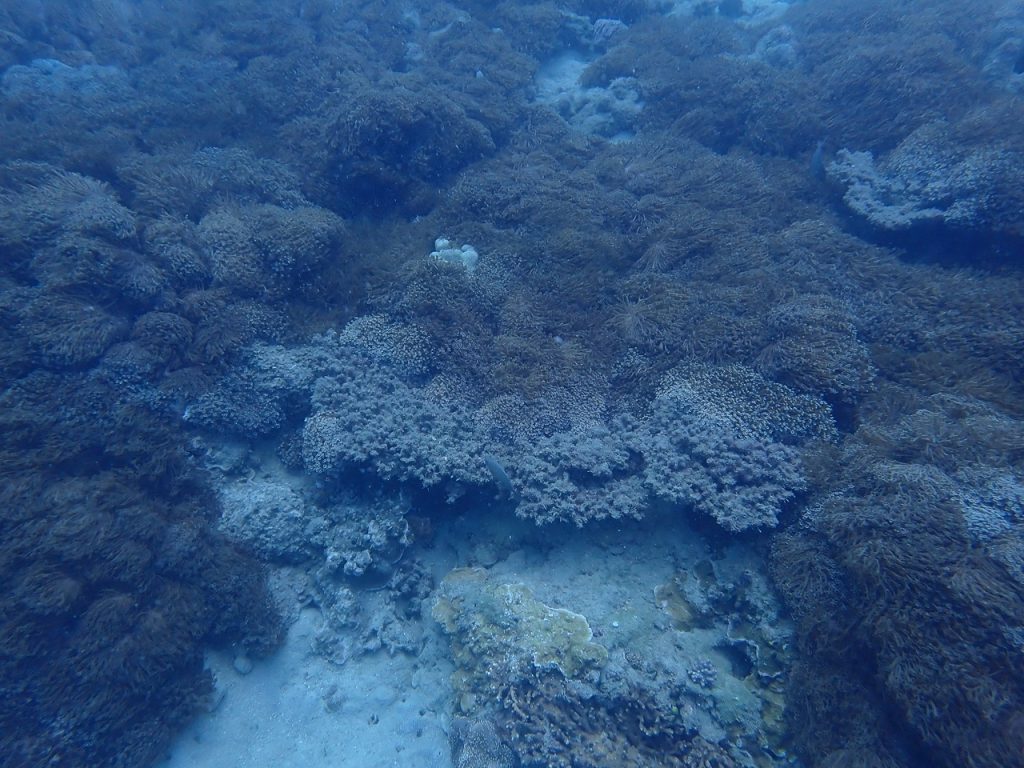
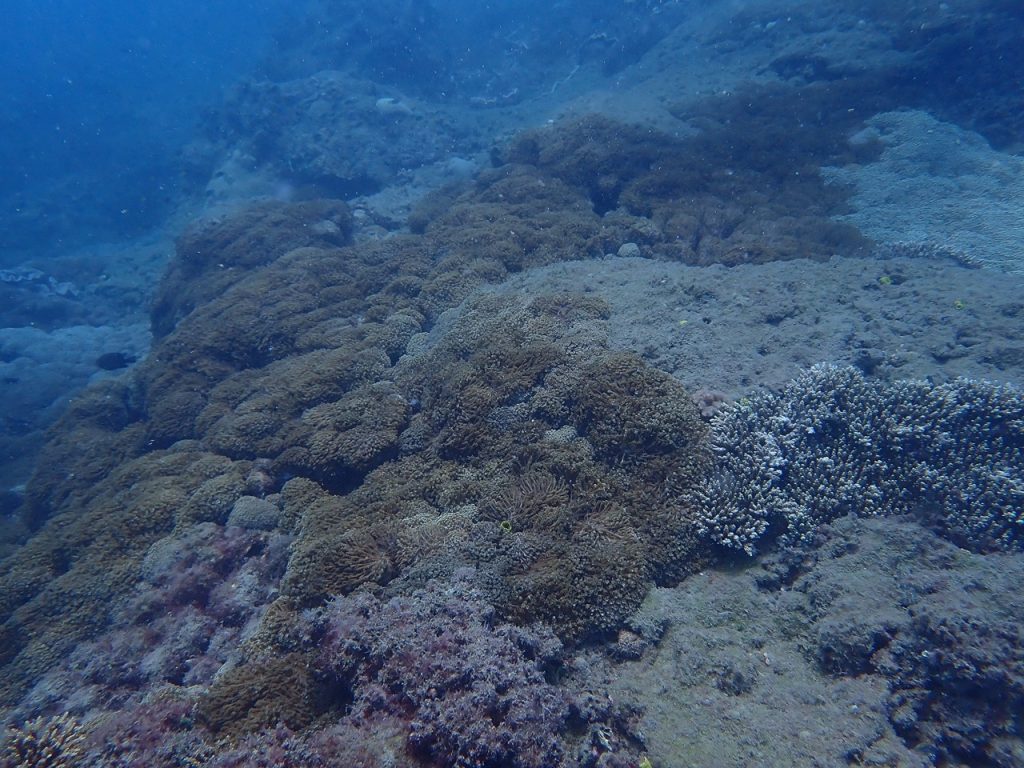
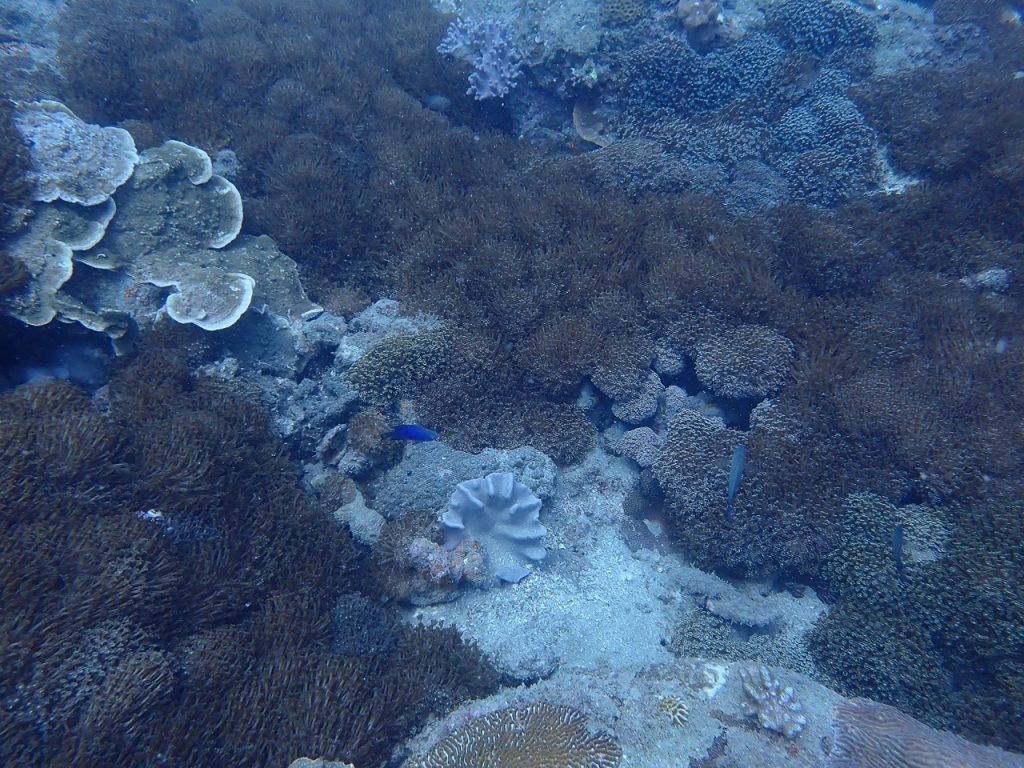
But what fascinated me most was not the abundance of fish, but the displacing of the fields of Acropora with Alveopora. As the branching Acropora disintegrated the Alveopora took hold. This was most noticeable at Bald Rocks reef because of the barrel sponges. They used to be surrounded by tall branching Acropora, now they are quite exposed with the structurally less complex and rather short Alveopora.
To be continued.
The tall branching Acropora have mostly all disintegrated, there is still evidence of some plate corals in the genus Acropora that are now dead, and there are areas of plate coral that are very much alive, even a bright green, that I will show in a next blog post.
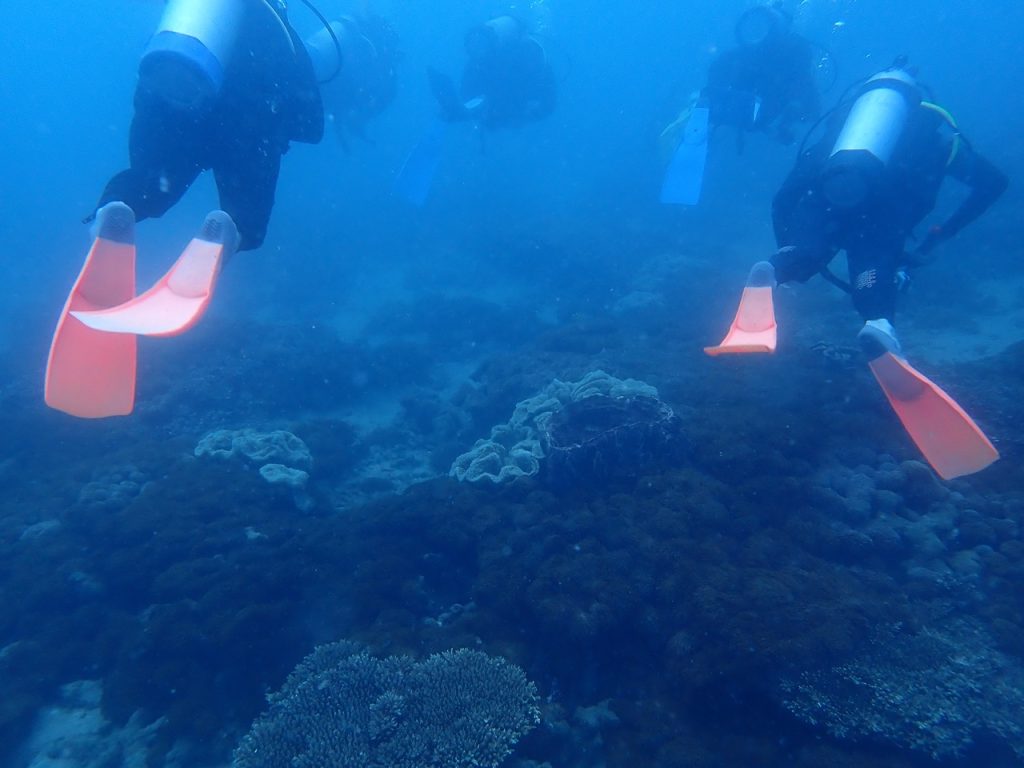
Scuba divers swimming over Alveopora where once there was Acropora, and the barrel sponge is still there. Sometimes there is a wobbegong shark hiding in it.
*Classification is fundamental to having a shared language for communicating changes in the distribution and abundance of plant and animal species, especially in the biological sciences. Having a binocular microscope was often important; for being able to know one species of plant or insect from another. By counting the number and knowing the shape, for example, of the spatula on the third instar larvae of a particular species of fly – I was able to describe 28 new species of plant-feeding gall midge from different species of acacia when I lived in Kenya. I didn’t do it by myself, I worked with Raymond J. Gagne at the Smithsonian Institute in Washington D.C.
Postscript.
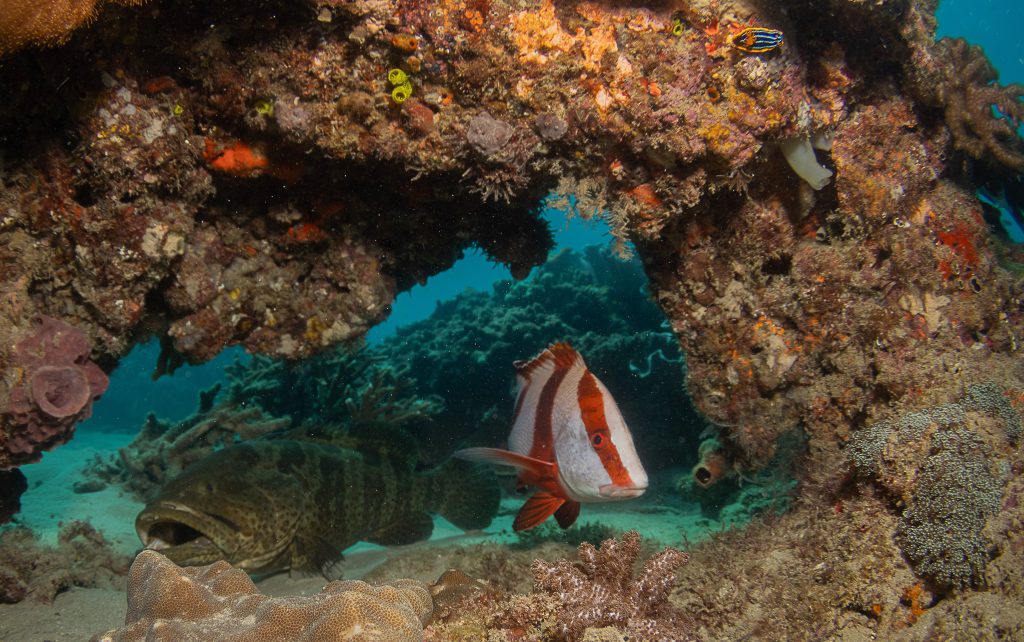
I was going to keep this photograph by Jenn Mayes from Wreck Beach reef over for another blog post, but it is too much fun to not keep sharing, this time with a focus on the Alveopora.