Good News: SEC’s ESG Plans Thwarted with Biden Term Ending

The news comes from Bloomberg Law article SEC’s Gensler Sees ESG Plans Thwarted as Biden’s Term Nears End. Excerpts in italics with my bolds and added images.

SEC Chair Gary Gensler started out with big plans on ESG.

  • Gensler seeks board diversity, workforce, ESG fund disclosures
  • Agency unlikely to finalize ESG regulations before January

The Democrat arrived at the Securities and Exchange Commission in 2021, after George Floyd’s murder in 2020 and President Joe Biden’s election that year fueled interest in environmental, social and governance investing. Gensler wanted public companies to report details about their climate change risks, workforce management and board members’ diversity.

He also sought new rules to fight greenwashing and other misleading ESG claims by investment funds.

Almost four years later, most of those major ESG regulations are unfinished, and they’ll likely remain so in the less than five months Gensler may have left as chair. A conservative-led backlash against ESG and federal agency authority has fueled challenges in and out of court to corporate greenhouse gas emissions reporting rules and other SEC actions, helping blunt the commission’s power.
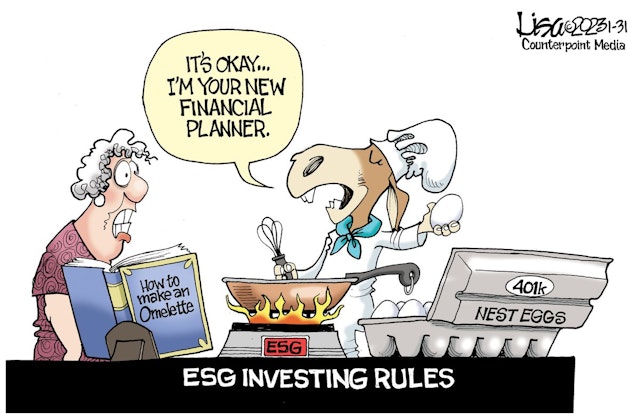
The climate rules—Gensler’s marquee ESG initiative—were watered down following intense industry pushback, then paused altogether after business groups, Republican attorneys general and others sued.

“It’s clear the commission leadership is exhausted and feeling buffeted by the courts, Congress and industry complaints,” said Tyler Gellasch, who was a counsel to former Democratic SEC Commissioner Kara Stein and is president and CEO of investor advocacy group Healthy Markets Association.

The SEC has finalized more than 40 rules since 2021, “making our capital markets more efficient, transparent, and resilient,” an agency spokesperson said in a statement to Bloomberg Law.

The spokesperson declined to comment on the status of the agency’s pending ESG rules, beyond pointing to the commission’s most recent regulatory agenda.

Long-standing plans to require human capital and board diversity disclosures from companies have yet to yield formal proposals. Final rules concerning ESG-focused funds still are pending, and even if the SEC adopts them before January as the agenda suggests, a Republican-controlled Congress and White House may have the power to quickly scrap them under the Congressional Review Act.
Unlike the workforce and board diversity rules that have yet to be proposed, investment fund regulations concerning ESG have already been drafted and are targeted for completion in October, according to the SEC’s latest agenda. ESG funds would have to disclose their portfolio companies’ emissions and report on their ESG strategies.

The SEC proposed the regulations in May 2022, along with rules intended to ensure ESG funds’ names align with their investments. The commission issued final fund name rules in September 2023.

The SEC’s investment fund proposal has raised objections from both funds and environmental and investor advocates.

The proposal would require environmentally-focused funds to disclose their carbon footprints, if emissions are part of their investment strategies. But it wouldn’t require funds that look at emissions to disclose other metrics that play a significant role in how they invest and the methodology they use to calculate those measures. The Natural Resources Defense Council, Interfaith Center on Corporate Responsibility, and other environmental and investor groups pushed for those requirements in an April letter to the SEC.

The Investment Company Institute, which represents funds, has raised concerns its members would have to report on their carbon footprints before public companies must disclose their emissions under SEC rules. The group in April called on the SEC to keep fund emissions reporting requirements on ice until the litigation challenging the agency’s public company climate rules is resolved. That litigation is at the US Court of Appeals for the Eighth Circuit, which is unlikely to rule this year.

The fund rules have received no Republican support at the SEC, with only Gensler and his fellow Democratic commissioners voting in favor of proposing them.

“If it’s a Republican Congress and Trump administration, you could imagine they would be willing to disapprove those,” said Susan Dudley, a George Washington University professor who oversaw the White House regulatory policy office under President George W. Bush.
 

via Science Matters

https://ift.tt/sNW2cgJ

September 14, 2024 at 10:04AM
Sunday

0 out of 10 based on 0 rating

via JoNova

https://ift.tt/KhTQLZg

September 14, 2024 at 09:33AM

The SEC’s Risky Plan to Decarbonize the U.S. Financial Markets

By Paul Tice

Reports of the impending death of the Environmental, Social, and Governance (ESG) movement have been greatly exaggerated.

While several sustainability-minded companies and Wall Street firms have recently adopted a lower ESG profile due to the public backlash, this is largely a tactical retreat until the government provides air cover. Financial regulators are now riding to the rescue, passing rules that make the entire climate-focused ESG system compulsory and prescriptive.

In March 2024, the Securities and Exchange Commission (SEC) issued final climate disclosure rules that require every large U.S. corporation to report in detail all the climate-related physical and transition risks faced by their businesses, along with the size of their carbon footprints.

The new SEC rules will force the management of all reporting companies to act as meteorologists and disclose every conceivable weather impact to their businesses over exceedingly long investment horizons, thereby reinforcing the climate change narrative. They will also discourage investment in the traditional energy sector by highlighting the outsize regulatory, litigation, contingent liability, and reputational risks now facing the industry due to government climate policies.

However, rather than de-risking the financial markets by improving disclosure for investors as promised by the SEC, the agency’s new rules will have the opposite effect. By imposing a climate test on all issuing and investing companies—basically, every financial market participant in the U.S.—the SEC’s goal is to help force the clean energy transition by stigmatizing carbon-emitting industries in general and specifically redirecting capital flows away from fossil fuel producers.

The SEC’s climate disclosure rules are part of the federal government’s coordinated climate plan and the latest piece in a sweeping regulatory attack on the oil and gas industry since President Biden took office. Defunding oil, gas, and coal companies arguably represents one of the most effective ways to shrink domestic hydrocarbon supply and cut national emissions.

Decarbonization, which the SEC’s rules will now abet and accelerate, is the real threat to the American economy and the U.S. financial markets. If the current administration succeeds in its goal of reducing U.S. net greenhouse gas emissions by 50%–52% by 2030 versus a 2005 baseline—on the way to net-zero emissions by 2050—the macroeconomic impact will be decidedly negative.

For starters, it will competitively hamstring the U.S. economy while doing nothing to solve the purported problem of global climate change since most developing countries—particularly China and India—are not playing by the same climate rules. Notwithstanding reports to the contrary, there is no global energy transition currently underway.  Since 1990, when the United Nations first started warning the world about the dangers of man-made global warming, annual global greenhouse gas emissions have increased by more than 50%, mainly due to the continued use of fossil fuels (especially coal) by developing countries.

Increased U.S. reliance on intermittent wind and solar power generation while simultaneously electrifying whole new swaths of the economy—starting with transportation—will strain and destabilize the American electricity grid and increase electricity prices across the board.

Constraining the domestic production of fossil fuels will lead to higher oil and gas prices, which will feed through the entire U.S. economy and raise the cost of almost everything, especially food. A regulatory-forced downsizing of the domestic oil and gas industry will also lead to significant job losses and shrink U.S. GDP, while the failure to maintain American energy independence will heighten national security risk for the country.

Germany’s recent economic woes show what lies in store for the U.S. if the Biden administration continues down its current climate policy path. Since embarking on its Climate Action Plan 2050 in 2016, Germany, the largest economy in Europe, has gone from the growth engine of the E.U. bloc to the “sick man of Europe” as climate-driven energy policy mismanagement has led to a downward spiral of deindustrialization and degrowth over the past decade.

There is no evidence that economic growth can be decoupled from emissions or fossil fuels. Aggressive emissions reduction during the current decade will result in a diminished U.S. economy by 2030, one marked by anemic growth, higher inflation, increased unemployment levels, and a hollowed-out domestic industrial base. It is difficult to see how such a macroeconomic backdrop would be constructive for Wall Street or Main Street.

Decarbonized financial markets will be, by definition, more volatile, riskier, and less diversified, with fewer investment choices for investors. Since energy-consuming industrial, utility, and technology companies represent the lion’s share of most benchmark U.S. stock and bond indexes, this will amplify the market’s exposure to fluctuating energy prices. Average U.S. corporate credit quality—especially for energy and other heavy industry—is also likely to trend lower by the end of the decade, with bankruptcy and debt default rates moving higher. By 2030, the U.S. may resemble an emerging country’s financial market more than a developed one.

The SEC has now stayed the implementation of its climate disclosure rules pending the resolution of the various lawsuits that are challenging the rulemaking on the grounds that it exceeds the agency’s statutory authority. Issuing climate disclosure rules as a backdoor means of changing the U.S. energy mix and restructuring the overall economy would seem to go well beyond the SEC’s role as the top cop for the U.S. financial markets.

Most egregiously, with these climate disclosure rules, the SEC will no longer be an objective market referee, at least when it comes to the ESG factor of climate change. The SEC will now become an active partisan player in the Biden administration’s drive to decarbonize the U.S. economy, in direct contravention of its regulatory mandate to remain impartial and simply ensure full disclosure and fair dealing across well-functioning financial markets. By mandating the integration of climate factors into both corporate policy and investment risk management, the agency will be supplanting the governance role of corporate executives, bank credit officers, and investment portfolio managers.

By attempting to achieve specific market outcomes based on an emissions litmus test, the SEC will also be picking corporate winners and losers and influencing asset pricing and financial market access by tilting the playing field away from traditional energy and other high-carbon-emitting sectors, which is an inversion—if not a perversion—of the SEC’s regulatory function.

Paul Tice is a senior fellow with the National Center for Energy Analytics and author of the new report “The SEC’s Climate Rules Will Wreak Havoc on U.S. Financial Markets.”

This article was originally published by RealClearEnergy and made available via RealClearWire.

via Watts Up With That?

https://ift.tt/vmeFqGL

September 14, 2024 at 08:07AM

Largest of the Saved Clams, Part 3. Inaugural Megafauna Expedition, September 2024

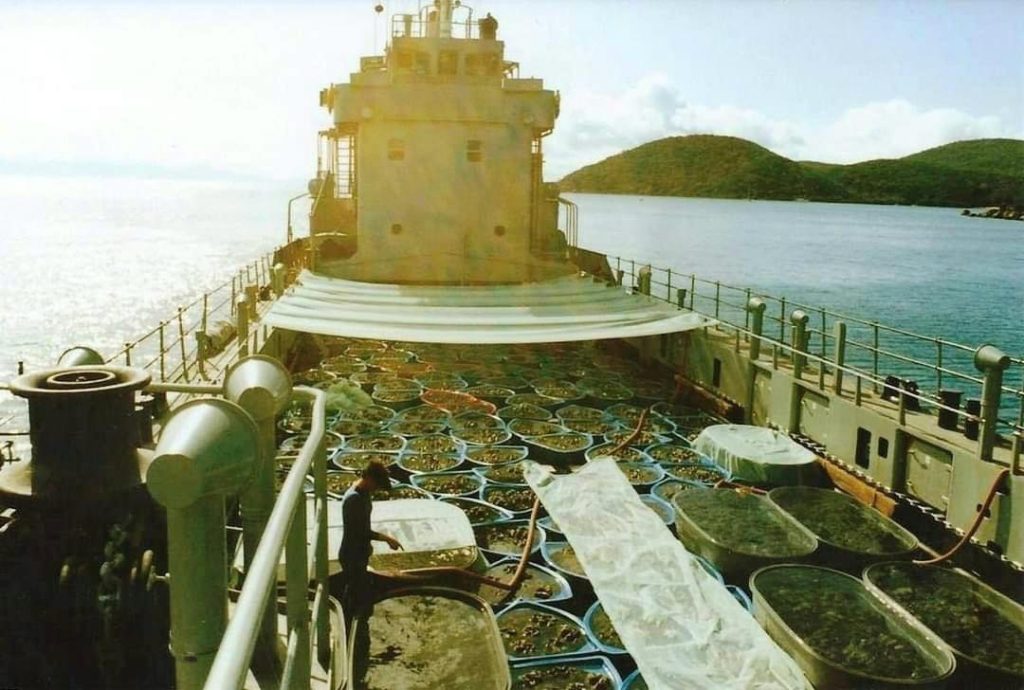
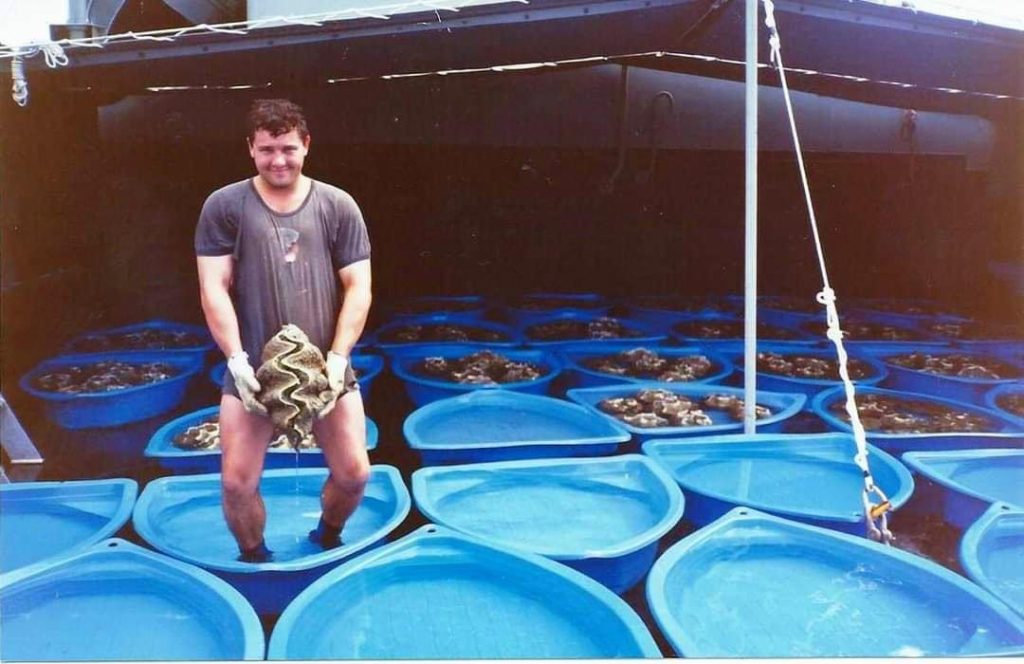
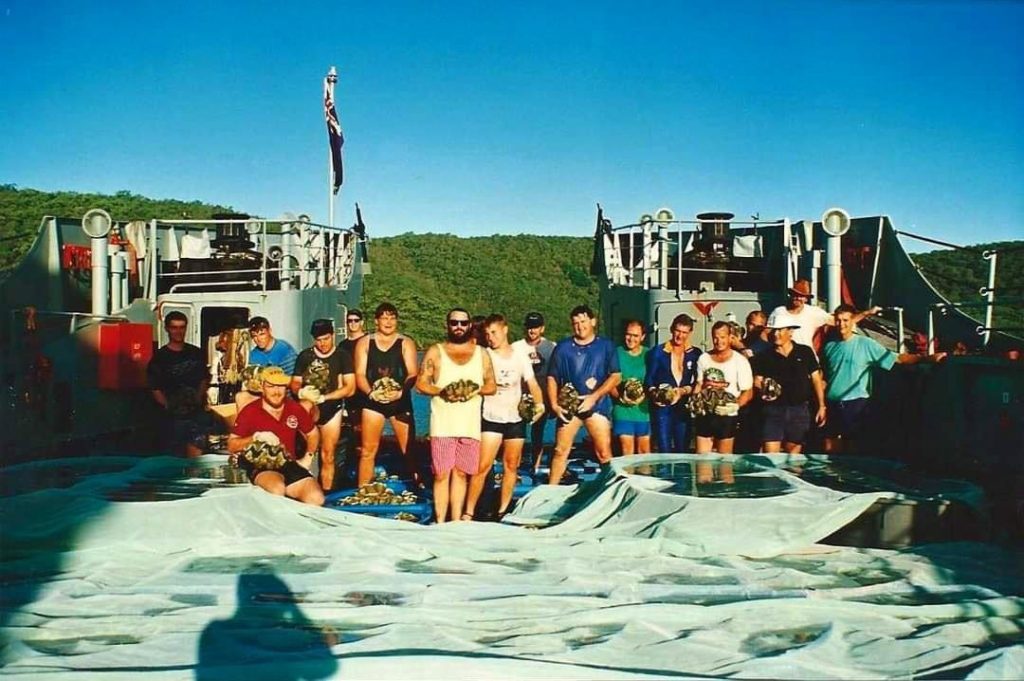
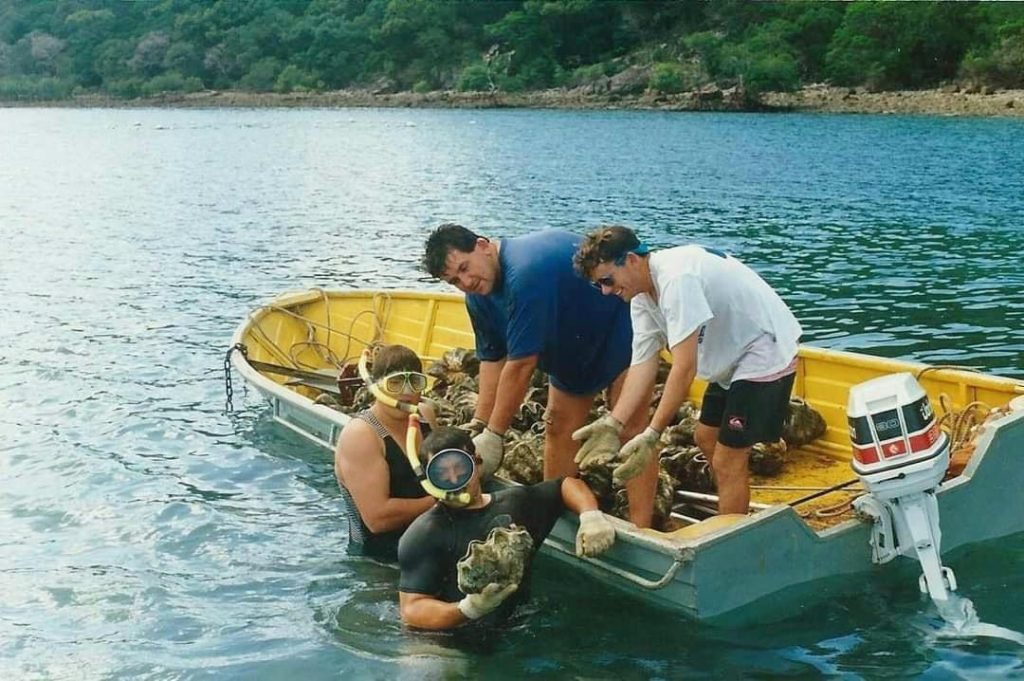
In May 1992, and again in March and April 1993, the Royal Australian Navy, specifically HMAS Tarakan, was involved in the translocation of tens of thousands of clams as part of Operation CLAMSAVER.  The clams were moved from a successful breeding program at Orpheus Island to various locations on the Great Barrier Reef, including to Grub Reef.

I am grateful to Jon Daly for providing me with some photographs from that time.

Daly wrote: “The guy in second from top photograph is Paul Livermore …  photograph of Tarakans tank deck covered in cheap plastic scallop shaped children’s paddling pools a continuous spray from the ship’s fire main …  I’m in the blue t-shirt, in two of the photographs … . [end quotes].  And I have more notes from other conversations with Jon Daly, for another time.

There appears to have been little if any follow-up, to know the fate of the clams.

Considering the photographic evidence from Jon Daly, the clams were not much more than 30cm in length when they were moved.    How big are they now?

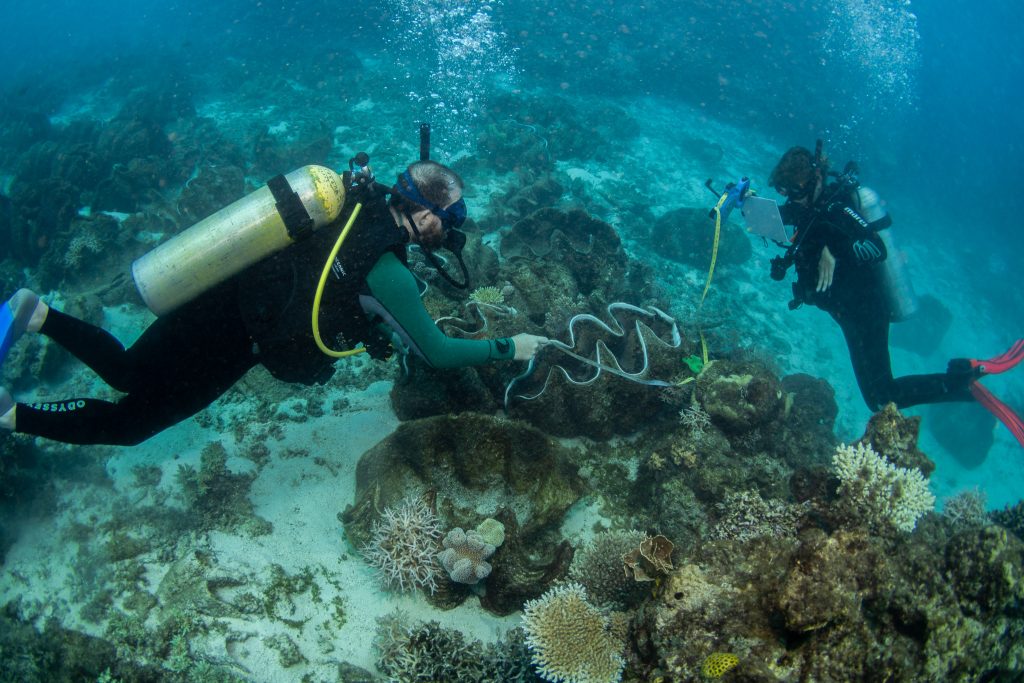
As part of the inaugural Megafauna Expedition – with the charter of the MV Sea Esta funded by Sydney-based philanthropist Simon Fenwick – we set off for Grub Reef on Wednesday, 4th September.

The skipper, Paul Crocombe, did some careful research and reconnaissance in advance of the expedition and was able to find one of the translocation sites for us.

Somehow, despite the blustery conditions, strong surface current and the ever-present risk of colliding with a one of the many bombies within such coral reef systems, Paul got the MV Sea Esta into Grub Reef and close to one of the translocation sites.

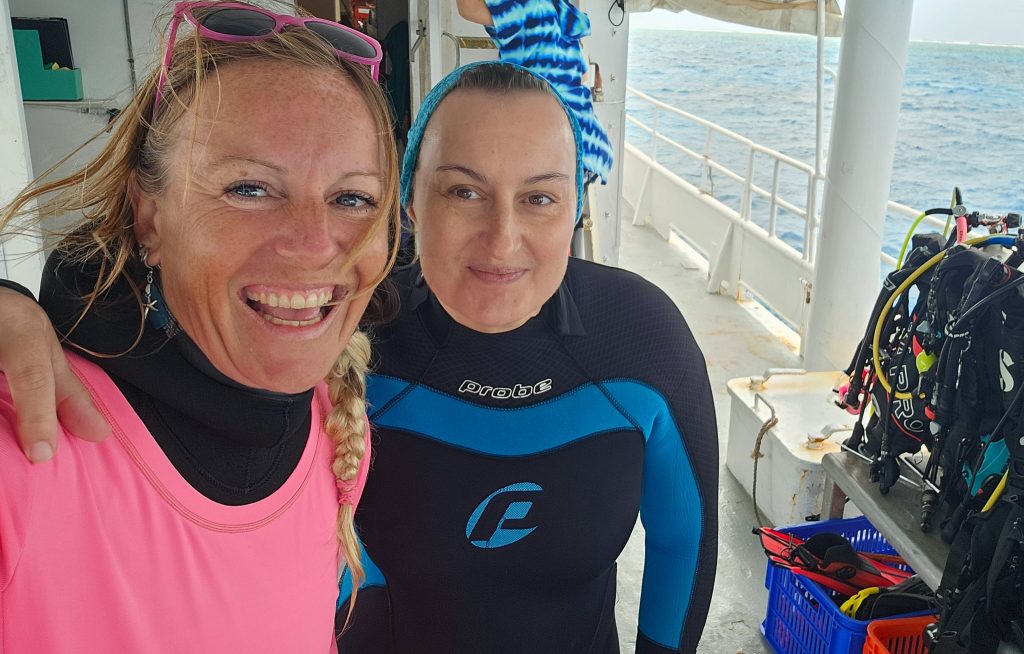
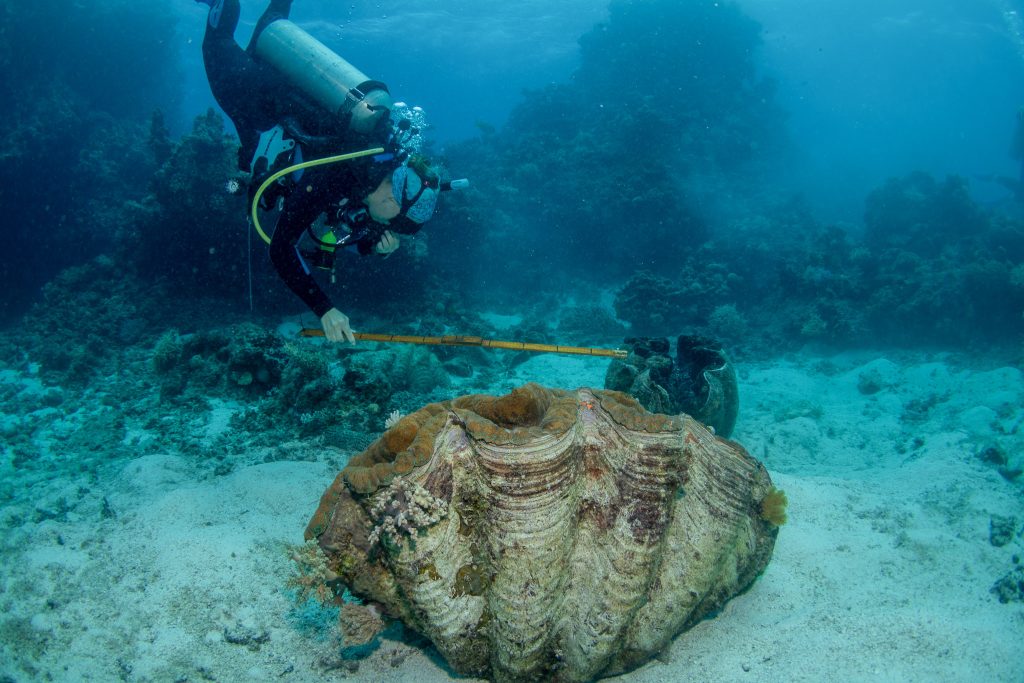
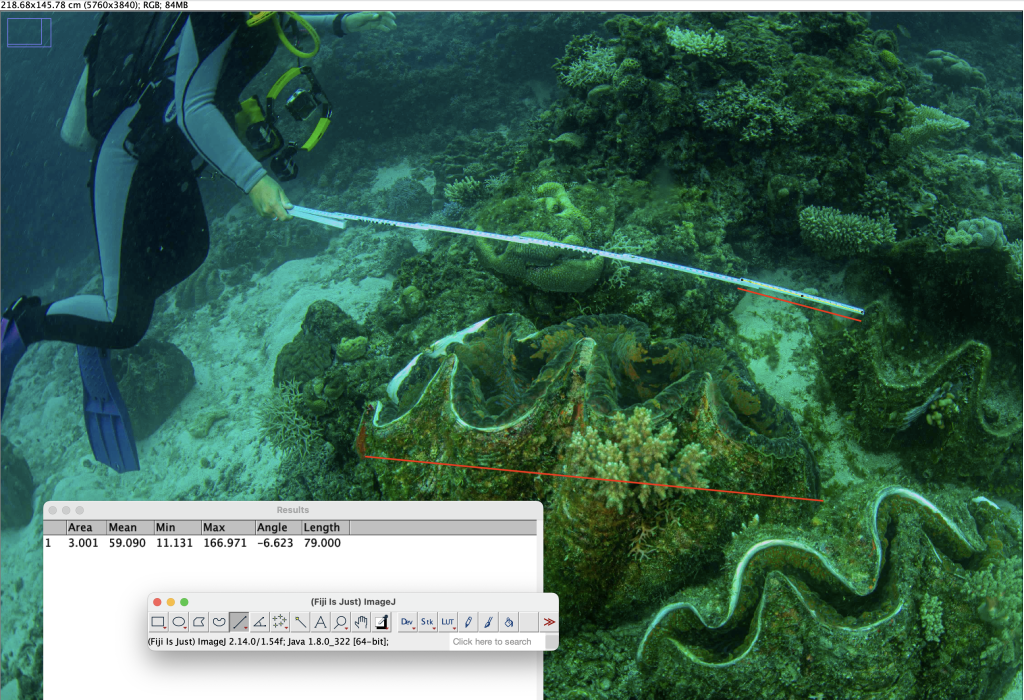
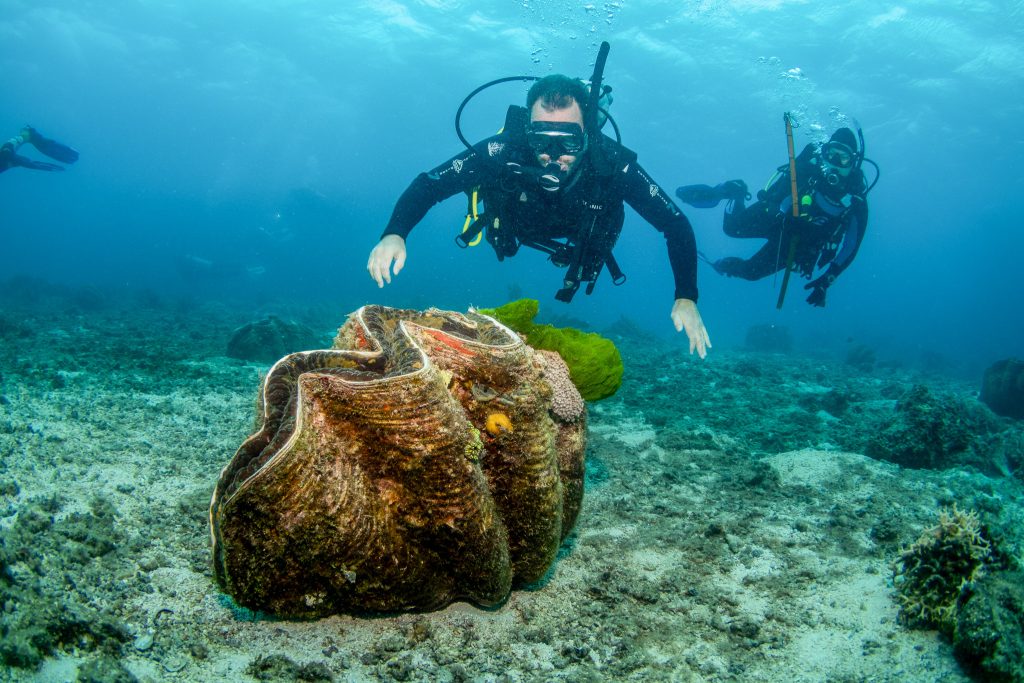
Underwater photographer Jenn Mayes with her scuba buddy Nadine Huth found and filmed the largest clam at 1.47 metres.  Congratulations!

Jenn Mayes (in pink) with her buddy Nadine Huth on the dive deck of the MV Sea Esta.

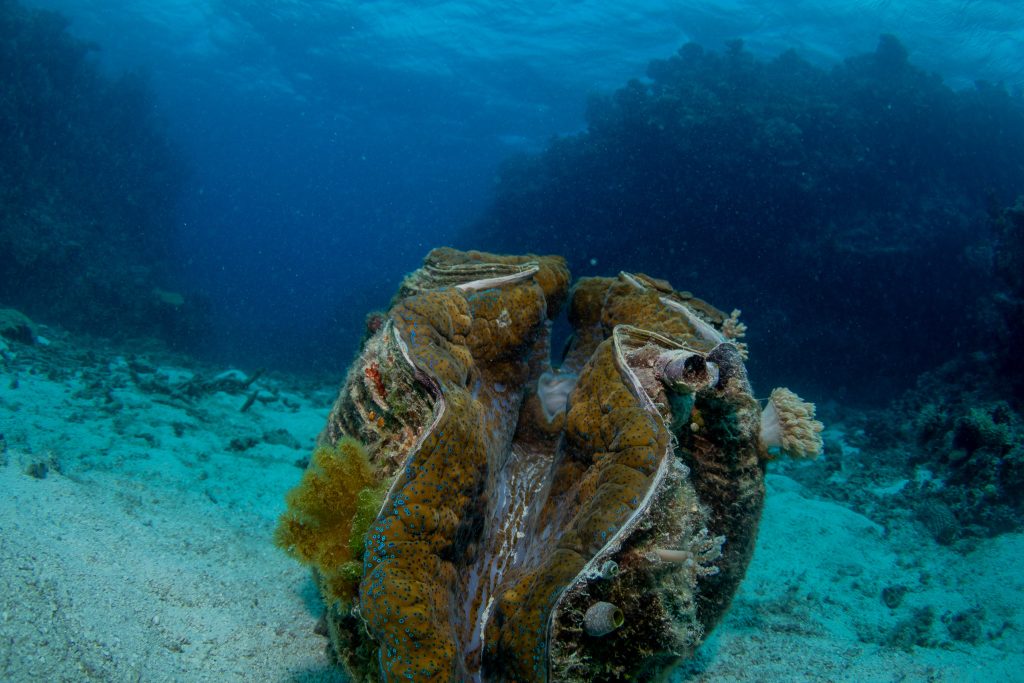
Winning photograph by Jenn Mayes with Nadine Huth holding the metre long ruler, in the category ‘largest clam’. The same clam is shown in the feature photograph at the very top of this blog post, and also below.   This is one of the clams saved by the Royal Australian Navy as part of operation CLAMSAVER.

There is so much more to tell, about that day and how it unfolded, giant clams, even a whale shark encounter for Dave Armstrong but without a photographer to capture the memory, and provide the evidence.

This story will be continued, including as part of a documentary film in production and about the inaugural Great Barrier Reef Megafauna Expedition.

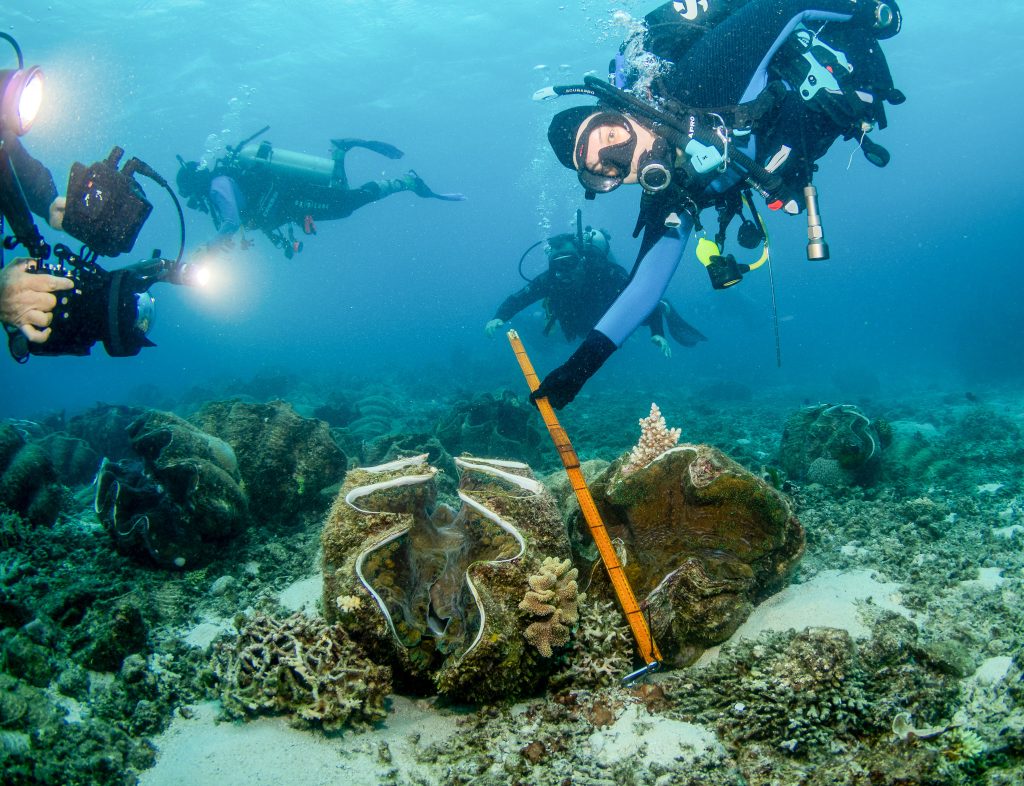
Rick Braley asked that we measure some clams, and we did.  There was a tape measure, and various other yardsticks being used by the expedition team.   The mean length of the clams measured on the first dive with the tape measure was 1.11 metres (n=6), and on the second dive was 0.91 (n=8).   These clams are all likely to be from the one cohort translocated from Orpheus Island.

Good job Dr Braley and the Royal Australian Navy!


via Jennifer Marohasy

https://ift.tt/W2EC6By

September 14, 2024 at 06:19AM